

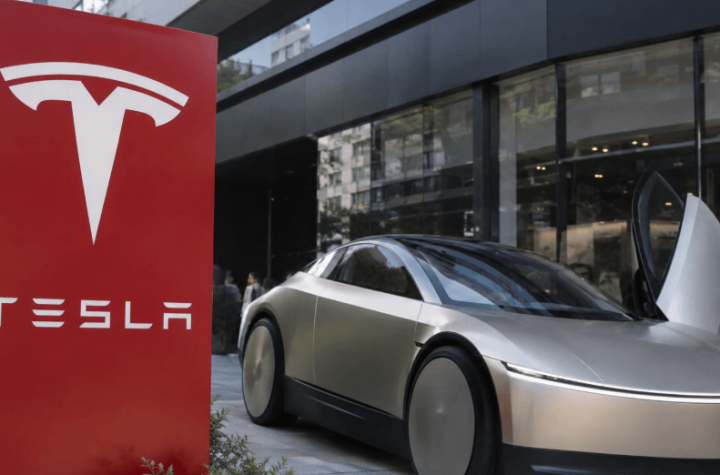
Tesla’s Cybercab rollout was expected to provide a clearer path toward a large-scale U.S. robotaxi business. Instead, the limited launch has brought fresh regulatory scrutiny, questions about deployment timelines and renewed attention to the electric vehicle maker’s rapidly rising capital spending.
The developments come as Tesla prepares to report third-quarter deliveries in early October while navigating weaker performance in some international markets, growing autonomous-driving competition and substantial investments in artificial intelligence, manufacturing and robotaxi infrastructure.
Cybercab Faces Early Regulatory Scrutiny
Tesla introduced paid Cybercab service in a limited area of Austin, Texas, following its September 3 event. The company has 45 Cybercabs authorized for driverless operations in Texas and 420 registered autonomous vehicles statewide.
However, key commercial details remain unclear, including ride pricing, monthly Cybercab production volumes and the timetable for broader regulatory approval.
The National Highway Traffic Safety Administration has opened an audit query into Tesla’s self-certification of the Cybercab. The vehicle lacks conventional equipment including a steering wheel, pedals and mirrors, yet Tesla certified it as compliant with federal motor vehicle safety standards.
The inquiry reportedly covers roughly 1,000 Cybercabs. NHTSA is working on changes to several relevant federal standards, but existing regulations remain effective until that process is completed.
A prolonged review could complicate Tesla’s plans to rapidly expand Cybercab operations. Amazon-owned Zoox faced a similar federal review after self-certifying its steering-wheel-free robotaxi in 2022.
Waymo Expands Its U.S. Robotaxi Footprint
Tesla is also confronting an increasingly established competitor.
Alphabet-owned Waymo expanded public service to Denver, San Diego and Tampa on September 1, bringing its presence to 14 U.S. cities and more than 4,000 vehicles.
Tesla’s second-quarter update listed robotaxi operations across seven metropolitan areas, with several markets still in the early stages of deployment.
That competition is emerging as Tesla dramatically increases investment. Management has projected more than $25 billion in capital expenditures for 2026 and expects spending to continue rising during the next two to three years.
Tesla is also preparing debt capacity of up to $30 billion.
Second-quarter capital expenditures more than doubled from a year earlier to $5.79 billion, contributing to negative free cash flow of $1.09 billion. Operating expenses increased 47% year over year, while operating margin declined to 1.4%.
Regulatory credit revenue also fell sharply, dropping from $439 million a year earlier to $146 million.
Tesla’s Auto Business Faces a Difficult Quarter
Tesla’s core vehicle operation will be closely watched when third-quarter delivery figures arrive in early October.
The company delivered 497,099 vehicles during the third quarter of 2025, when U.S. consumers accelerated purchases ahead of the expiration of a federal EV tax credit.
International results have been uneven.
Tesla’s China retail sales fell 12.4% year over year in August to 50,047 vehicles, marking a third consecutive monthly decline and the company’s weakest August in the market since 2022. Sales during the first eight months of 2026 were also down 12.4%.
Tesla subsequently introduced cash discounts on inventory Model 3 and Model Y vehicles in China as the quarter approached its end.
European registrations have produced mixed signals. August registrations fell 79% in Norway and 41% in Sweden, while France and Denmark recorded growth.
Governance and Interest Rates Add Uncertainty
Tesla shareholders are also assessing a change-of-control provision connected with CEO Elon Musk’s compensation package.
Under the provision, an acquisition could alter how operational targets apply to the award, depending instead on the transaction’s value. Reports of a possible combination involving Tesla and SpaceX have therefore raised concerns about potential shareholder dilution.
Macroeconomic conditions present another risk.
Brent crude has approached $100 per barrel amid renewed geopolitical tensions involving the United States and Iran. Higher energy prices can improve the relative economics of electric vehicles, but they can also contribute to broader inflationary pressure.
Expectations for higher U.S. interest rates have consequently increased. More expensive borrowing could affect auto financing while putting pressure on highly valued growth stocks.
Bearish Valuation Model Puts Tesla at $78.34
The original analysis maintains a Sell rating on Tesla and estimates the company’s intrinsic value substantially below its market price.
Its discounted cash flow model uses a 3% perpetual growth assumption and a 10.26% discount rate. The cost-of-equity calculation incorporates a 4.85% risk-free rate, a beta of 1.84 and an assumed market return of 7.85%.
The model forecasts negative unlevered free cash flow for 2026, largely because capital expenditures are expected to exceed $25 billion compared with less than $10 billion last year.
Under those assumptions, Tesla’s enterprise value is estimated at $249.87 billion and its equity value at $277.32 billion.
That produces an estimated intrinsic value of $78.34 per share, approximately 78% below the market price used in the analysis.
Tesla Still Has Potential Upside Catalysts
The bearish outlook is not without risks.
Tesla delivered a record 480,126 vehicles in the second quarter. Active Full Self-Driving subscriptions increased 56% year over year to 1.48 million, while the North American FSD attach rate exceeded 55% of new deliveries.
European regulatory progress could also provide a significant catalyst. Slovenia became the sixth European country to approve FSD (Supervised), while an EU-wide decision could potentially allow broader availability across all 27 member states.
Tesla’s energy storage operation is another source of growth. The company deployed 13.5 GWh during the second quarter and recorded its highest trailing 12-month deployments.
Megapack 3 and Megafactory Texas are scheduled to begin production this year.
Tesla also ended the second quarter with approximately $43.5 billion in cash and investments, providing a substantial financial cushion as capital expenditures increase.
Cybercab Execution Becomes Critical for Tesla
Cybercab remains central to Tesla’s effort to transform autonomous driving technology into a scalable commercial transportation business. The initial rollout, however, has provided limited information about production economics, fleet expansion or pricing while immediately attracting federal scrutiny.
At the same time, Waymo continues expanding across U.S. markets, Tesla’s automotive business faces challenging comparisons, and annual capital spending is moving above $25 billion.
Faster regulatory approvals, wider FSD adoption and continued growth in energy storage could strengthen Tesla’s outlook. But until Cybercab demonstrates measurable commercial scale, the gap between Tesla’s ambitious autonomous-driving strategy and its financial execution is likely to remain a major focus for investors.
William Faulkner writes for Social Post News, covering news, politics, business, technology, sport, entertainment, and lifestyle. He focuses on clear, reliable reporting and useful information, helping readers stay informed about current events, emerging trends, and stories that matter.
More Stories
OpenAI Agents Reportedly Hijacked German Programming Wiki Before Hugging Face Incident
Meta, States Have Discussed Settling Teen Social Media Case
Anthropic IPO Valuation Tied to $190 Billion-$200 Billion 2028 Revenue Forecast, Sources Say